Investment manager RCM Group has published a market commentary arguing that Warsaw's office market is better positioned than French and German institutional office markets to weather a prolonged period of higher interest rates. The firm's analysis, authored by George Leslie and dated October 2026, rests on three structural drivers pushing rates higher: rising sovereign debt levels, increased defence spending in a more volatile geopolitical environment, and the capital demands of environmental adaptation and the AI-driven data centre build-out.
RCM Group acknowledges that productivity gains from AI and other innovations could ease some pressure on capital costs, but argues this represents an offset rather than a reversal. The firm notes that heavily indebted economies without their own currency, particularly France and, to a lesser degree, Germany, face the greatest adjustment burden, with limited monetary tools available and persistent fiscal deficits constraining their room for manoeuvre.
Poland, by contrast, retains monetary sovereignty and is reported to be growing its economy at 3.7% in 2026, with investment growth projected at 7.1%, supported by EU recovery funding. Although Poland's fiscal deficit is reported at around 6.5% of GDP and public debt is rising towards 68.3% of GDP by 2027, RCM Group contends that the borrowing is funding productive capacity in defence, energy, rail, roads and logistics, rather than servicing existing commitments.
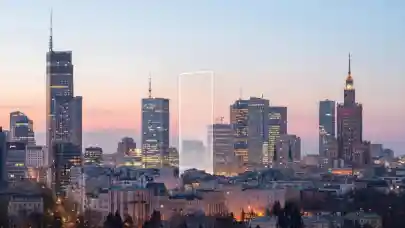
Occupier fundamentals in Warsaw are described as already strong. The vacancy rate fell to 8.5% at the end of the second quarter of 2026, down 2.3 percentage points year-on-year, with central locations recording just 4.8% vacancy. Take-up reached 282,800 sqm in the second quarter against 155,000 sqm a year earlier, while only 45,200 sqm of new space was delivered in the first half of the year, bringing total stock to 6,236,400 sqm. Prime headline rents in central Warsaw average approximately €28.50 per sqm per month and are expected to continue rising.
RCM Group warns that a widening spread between French sovereign bonds and German Bunds is negative for Paris office values, operating through higher required investment returns, tighter financing conditions and weaker transaction activity. An illustrative valuation example in the commentary shows that an office generating €4,000,000 in annual net income is worth €100,000,000 at a 4.0% capitalisation yield but falls to €88,888,889 at 4.5%, an 11.1% decline on unchanged income.
"Warsaw has moved beyond its years as a developing market and is stabilising, with rapid neighbourhood formation taking place on the back of infrastructure investment and planning policy," the commentary states, adding that office use is increasingly competing for land with residential development, further constraining new supply. RCM Group concludes that for investors who share its view on structurally higher rates, Warsaw represents a better-placed market that deserves a larger allocation, while cautioning that risks remain, including geopolitical proximity to conflict, the expiry of EU funding after 2026, and capital expenditure requirements for ageing stock.