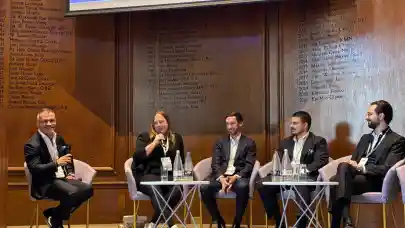
European real estate investors are navigating a market where higher financing costs and geopolitical uncertainty continue to weigh on sentiment, but improving liquidity, rental growth and renewed capital flows are creating opportunities across the risk spectrum. Speaking at the Real Estate Capital & Investment Decisions Forum 2026 in London, co-organised by Property Forum and RICS, investors discussed how strategies are shifting towards resilient income, active asset management and carefully selected value creation opportunities.
Jennifer Stillman, Investment Director, Real Assets/Private Credit at Aberdeen Investments, highlighted the contrasting signals coming from different parts of the capital market. Core real estate fundraising remains difficult, with substantial outflows from private funds and the UK pooled fund universe, while US REITs have been bringing significant capital into the European market. Aberdeen has nevertheless become more positive on the breadth of investable sectors. Alongside its established exposure to residential and logistics, the company is returning to retail and offices, including recent investments in London's West End and Bond Street. Stillman stressed that constrained development is supporting rental growth in several markets, providing an important source of returns even as core capital remains relatively scarce. In private credit, Aberdeen primarily focuses on long-dated, investment-grade financing, including infrastructure, housing and affordable housing, rather than the higher-return strategies increasingly associated with the private credit label.
Miles Skinner MRICS, Head of Investment Management UK & Ireland at Union Investment Real Estate, said the environment remains particularly challenging for core investors as real estate competes with other financial asset classes while financing costs and currency hedging put additional pressure on returns. This is pushing the investor selectively towards core-plus opportunities, although any additional risk must be carefully controlled. Rather than relying on financing assumptions or yield compression to generate returns, Union Investment is concentrating on sustainable income, disciplined underwriting and resilient cash flows. The company is increasingly willing to take on refurbishment and repositioning opportunities where capex can unlock rental growth, while generally avoiding ground-up development. Skinner also stressed that ESG remains directly connected to financial performance through financing conditions, occupier demand and long-term asset value. Regional UK markets can also offer attractive opportunities, with Edinburgh cited as an example where limited supply and planning constraints support rental growth.
Mihai Paduroiu, CEO Office and Commercial Division at One United Properties, argued that CEE markets remain structurally attractive despite international capital currently being less active in Romania than in markets such as Warsaw and Prague. Residential demand remains strong, while Bucharest offers higher office yields and significant long-term growth potential. Against a relatively illiquid transaction market, One United Properties is preparing to transfer its fully let prime office portfolio into a REIT-like structure designed to attract institutional and retail capital seeking income-producing Romanian real estate. The vehicle is expected to start with a gross asset value of just under €600 million and target €1 billion relatively quickly, with the company aiming for a dividend above 7% and annual growth of 3-5%. Paduroiu expects international capital flows into CEE to strengthen, arguing that the region combines attractive pricing with greater growth potential and market participants that have become accustomed to operating through repeated periods of economic and financial disruption.
Nicolo Benzi, Investment Director at Patron Capital, described a more positive environment for opportunistic and value-add investors, particularly as North American capital shows renewed interest in Europe. Rather than making large sector or geographic bets, Patron focuses on mid-market opportunities where returns can be generated through asset-specific value creation. Current strategies range from residential investments and development in Spain to multi-let industrial assets in markets including the Netherlands, Germany and the UK. Entry pricing, capex opportunities and the ability to capture rental reversion remain central to the investment case. Patron is also expanding beyond equity through a recently launched private credit strategy, targeting returns of around 11-13% and focusing initially on the UK, including refurbishment financing. Benzi said liquidity has improved compared with 12 months ago, while investors have become faster at pricing geopolitical shocks into their decisions. He therefore described Patron's outlook as somewhat more bullish than a year earlier.
The discussion, chaired by Michał Piasek, Associate Director | Advisor, Corporate Finance & Living Services CEE at Colliers, ultimately revealed a market without a single dominant view on the next phase of the cycle. Benzi was somewhat more bullish than a year ago, Paduroiu's outlook was broadly unchanged, while Skinner had become somewhat more bearish as earlier optimism among core investors faded. Stillman also remained broadly unchanged. The audience leaned somewhat more bearish, although a significant share saw little change from 12 months earlier. The common thread across the panel was that investors can no longer rely on cheaper financing and yield compression to deliver performance: income growth, operational expertise, disciplined underwriting and active value creation are becoming increasingly important drivers of returns.