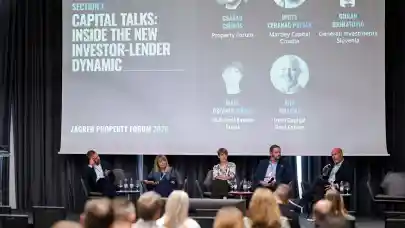
Croatia and Slovenia are attracting growing volumes of real estate capital, but investors are increasingly competing for a limited pool of institutional-quality assets. At Zagreb Property Forum 2026, speakers on the opening panel discussed pricing, investment strategies, financing conditions and the growing need for creativity as the region’s real estate markets mature.
Mirta Ceranac Poljak, Managing Director, Martley Capital Croatia, said the shortage of suitable institutional product is being compounded by pricing that does not always reflect differences in asset quality. Core and value-add properties are often being marketed at similar pricing levels, limiting opportunities for investors with different strategies. Martley Capital remains focused on Croatia and Slovenia, where regional knowledge provides an advantage, while markets such as Austria and Slovakia currently offer lower yields and greater competition. Looking ahead, the company is working towards an office investment and exploring retail park and logistics opportunities. Hotels could also become investable where transactions can be structured around rental income, but operational exposure to resorts does not fit the fund’s real estate investment approach.
Goran Djuratović, Director of Financial Advisory and Sales, Generali Investments Slovenia, expects competition to intensify further as international investors increasingly look at Croatia and Slovenia and yields compress. He argued that the next stage of market development could involve a broader mix of core and value-add opportunities, greater cross-border investment and more co-investment structures. Generali is interested in offices, retail parks and potentially private healthcare, while logistics remains attractive but difficult to access because developers frequently retain assets themselves. Rising financing costs are a growing consideration, making tenant quality, equity levels and co-investment increasingly important. At the same time, competition from family offices, high-net-worth individuals and mezzanine funds is giving borrowers alternatives to traditional bank financing and strengthening their negotiating position.
Maja Ostanek MRICS, Director, ALFI Real Estate Fund, highlighted both the scarcity of investment products and the risk of buying assets at low yields combined with rental levels that may prove difficult to sustain. She expects further yield compression as investors from markets including Czechia and Slovakia enter the region, but warned that premium office rents above €20 per sqm have a relatively limited tenant base in Slovenia and Croatia. ALFI is therefore becoming more cautious about new office acquisitions while expanding into other sectors. The fund has secured a logistics asset through an off-market sale-and-leaseback transaction, has two retail parks in Slovenia and Croatia in its pipeline and is negotiating a hotel investment backed by a lease agreement. She also noted that banks have become more flexible in structuring financing, helping investors execute transactions even as interest rates become less favourable.
Arn Willems, President of the Management Board, InterCapital Real Estate, said the fund has built a diversified portfolio of approximately €200 million across Croatia and Slovenia since completing its first acquisition last year and has a strong pipeline for 2027. While competition is increasing, he stressed that Croatia still offers an attractive spread between property yields and the cost of debt, although that advantage has recently started to narrow. Given the relatively small and shallow nature of the Zagreb market, he also urged caution over apparently strong office fundamentals, as even a comparatively modest development pipeline could quickly affect vacancy and rents. InterCapital therefore focuses on finding the right balance between price, income and asset quality rather than relying on future rental growth or yield compression to generate returns. The same principle applies to financing: debt should enhance returns rather than make an otherwise weak investment case work.
The discussion also pointed to continued investor appetite for real estate as an inflation hedge. Index-linked rents are supporting the sector’s appeal, while fund managers are seeing demand from both institutional and high-net-worth investors. Although rising interest rates, yield compression and limited product availability could make transactions more challenging, the panellists broadly described Croatia and Slovenia as markets that are continuing to mature, with new capital and more sophisticated financing and investment structures gradually widening the opportunity set.