Romania's industrial and logistics market has slowed in 2026 following a record 2025. In the first nine months, publicly reported leasing transactions reached approximately 450,000 sqm, around 30% below the level recorded in the same period last year, according to Colliers data. Bucharest-Ilfov accounts for nearly 60% of the total volume, though infrastructure development is beginning to reshape the demand map across the country. Transaction volumes remain close to the ten-year average for the first three quarters and are more than 40% above the 2017–2019 average.
"It is important to put these figures in the context of 2025, which was a record year for Romania, with almost one million sqm of reported leasing transactions. It was natural for the pace to be more moderate in 2026. Interest in Romania remains, both for manufacturing and logistics, but companies are more cautious given the current international context, and decision-making is taking longer," said Victor Coșconel, Partner and Head of Leasing for Office and Industrial Agencies at Colliers.
Bucharest-Ilfov generated approximately 265,000 sqm of transactions in the first nine months, down around 41% from the same period in 2025. Outside the capital, volumes fell by less than 10%, from approximately 204,000 sqm to around 186,000 sqm, demonstrating greater resilience. Infrastructure is increasingly influencing demand patterns: three of the five largest transactions in the Bucharest-Ilfov region were concluded in areas that until recently had a limited logistics presence, including VGP Park Bucharest A2 to the east and CTPark Bucharest South, both benefiting from completion of southern sections of the A0 motorway. Colliers expects new infrastructure to have a similar effect in other regions, with Moldova identified as having growth potential as major projects advance.
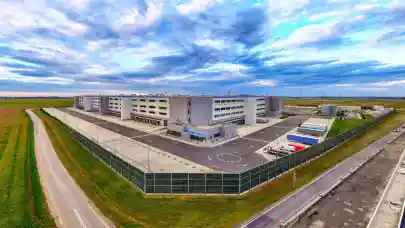
On the supply side, deliveries in the first nine months exceeded 300,000 sqm, pushing total leasable stock beyond 8.3 million sqm. Notable completions include a 56,000 sqm warehouse developed by CTP in western Bucharest for LPP and an approximately 46,000 sqm project developed by VGP north of the capital. Prime rents for a well-located built-to-suit project of approximately 5,000 sqm remain in the €4.5–5 per sqm per month range, though transactions are currently closing closer to the lower end. Greater competition among landlords, sublease availability and the international economic climate are giving tenants more negotiating power, while construction costs, up more than 10% over the past year, limit the scope for deeper rental reductions. Vacancy rates remain below 10% in most areas.
"As long as external uncertainties persist, we may see several more quarters with a pace similar to that of 2026. The market's evolution points to a normalisation following the record year of 2025, with greater selectivity and a more measured pace of decision-making, rather than a structural shift. Consumption is beginning to stabilise, while manufacturing investment continues. Romania remains on the radar of companies considering relocating or bringing production activities closer to European markets, and 2027 could be a more active year," added Victor Coșconel.
Manufacturing accounted for approximately 28% of industrial and logistics demand in the first half of the year, while investment in machinery and equipment grew by more than 18% in volume terms over the same period. At EMEA level, the vacancy rate stood at 5.8% in the second quarter, the Colliers index for space under construction was 16.5% below last year's level, and 70% of markets analysed expect rents to remain broadly stable over the next 12 months. Colliers anticipates a positive medium-term outlook at European level, supported by demand for modern space, the need for resilient supply chains and investment in advanced manufacturing and the defence sector.