The office markets of Central European capitals are growing dynamically: the number of new leases is on the rise, vacancy rates have hit record lows in several cities and demand for large office space is also growing. In light of all this it is no surprise that development activity is also heating up on the most popular markets of the region. We asked three major office developers to tell us which city in the region offers the most attractive development opportunities, how tenants’ requirements are changing and what makes Central European capitals different.
The full version of this article will be published in the next issue of Portfolio Property Magazine, to be distributed at CEE Property Forum 2017 in Vienna on 19 September.
Balázs Biacs, Head of Acquisitions, TriGranit
New office developments can be profitable in any Central European city, where there is stable or steadily growing demand for new office space, where investors are interested in new projects and there is no significant risk of oversupply on the market. A qualified and educated labour force with good language skills is the main premise for strong demand from tenants, but the presence of quality higher education and international airports are also important aspects. Cities like Krakow, Katowice, and of course Bratislava and Budapest, are attractive to well-qualified workers as they are among the most important educations centres of the region. The positive investment sentiment that characterises the region currently can be felt in every country in CEE. Significant transactions have been closed in the office segment in Romania, Hungary and Slovakia. In Poland, secondary cities have also appeared on the map of international institutional investors; cities such as Tricity, Krakow and Katowice have stable investment markets and they offer outstanding growth potential to investors. Even though Romania is perceived as a more challenging market and financing conditions are different than in the rest of CEE, our expectations are positive for the country. The Romanian office investment market is increasingly institutional but it is yet to see the depth of investors that are present in other CEE countries. Unlike in other CEE countries, there are no secondary office locations on the rise in Hungary and Slovakia, the capitals continue to act as the centre of the labour market.
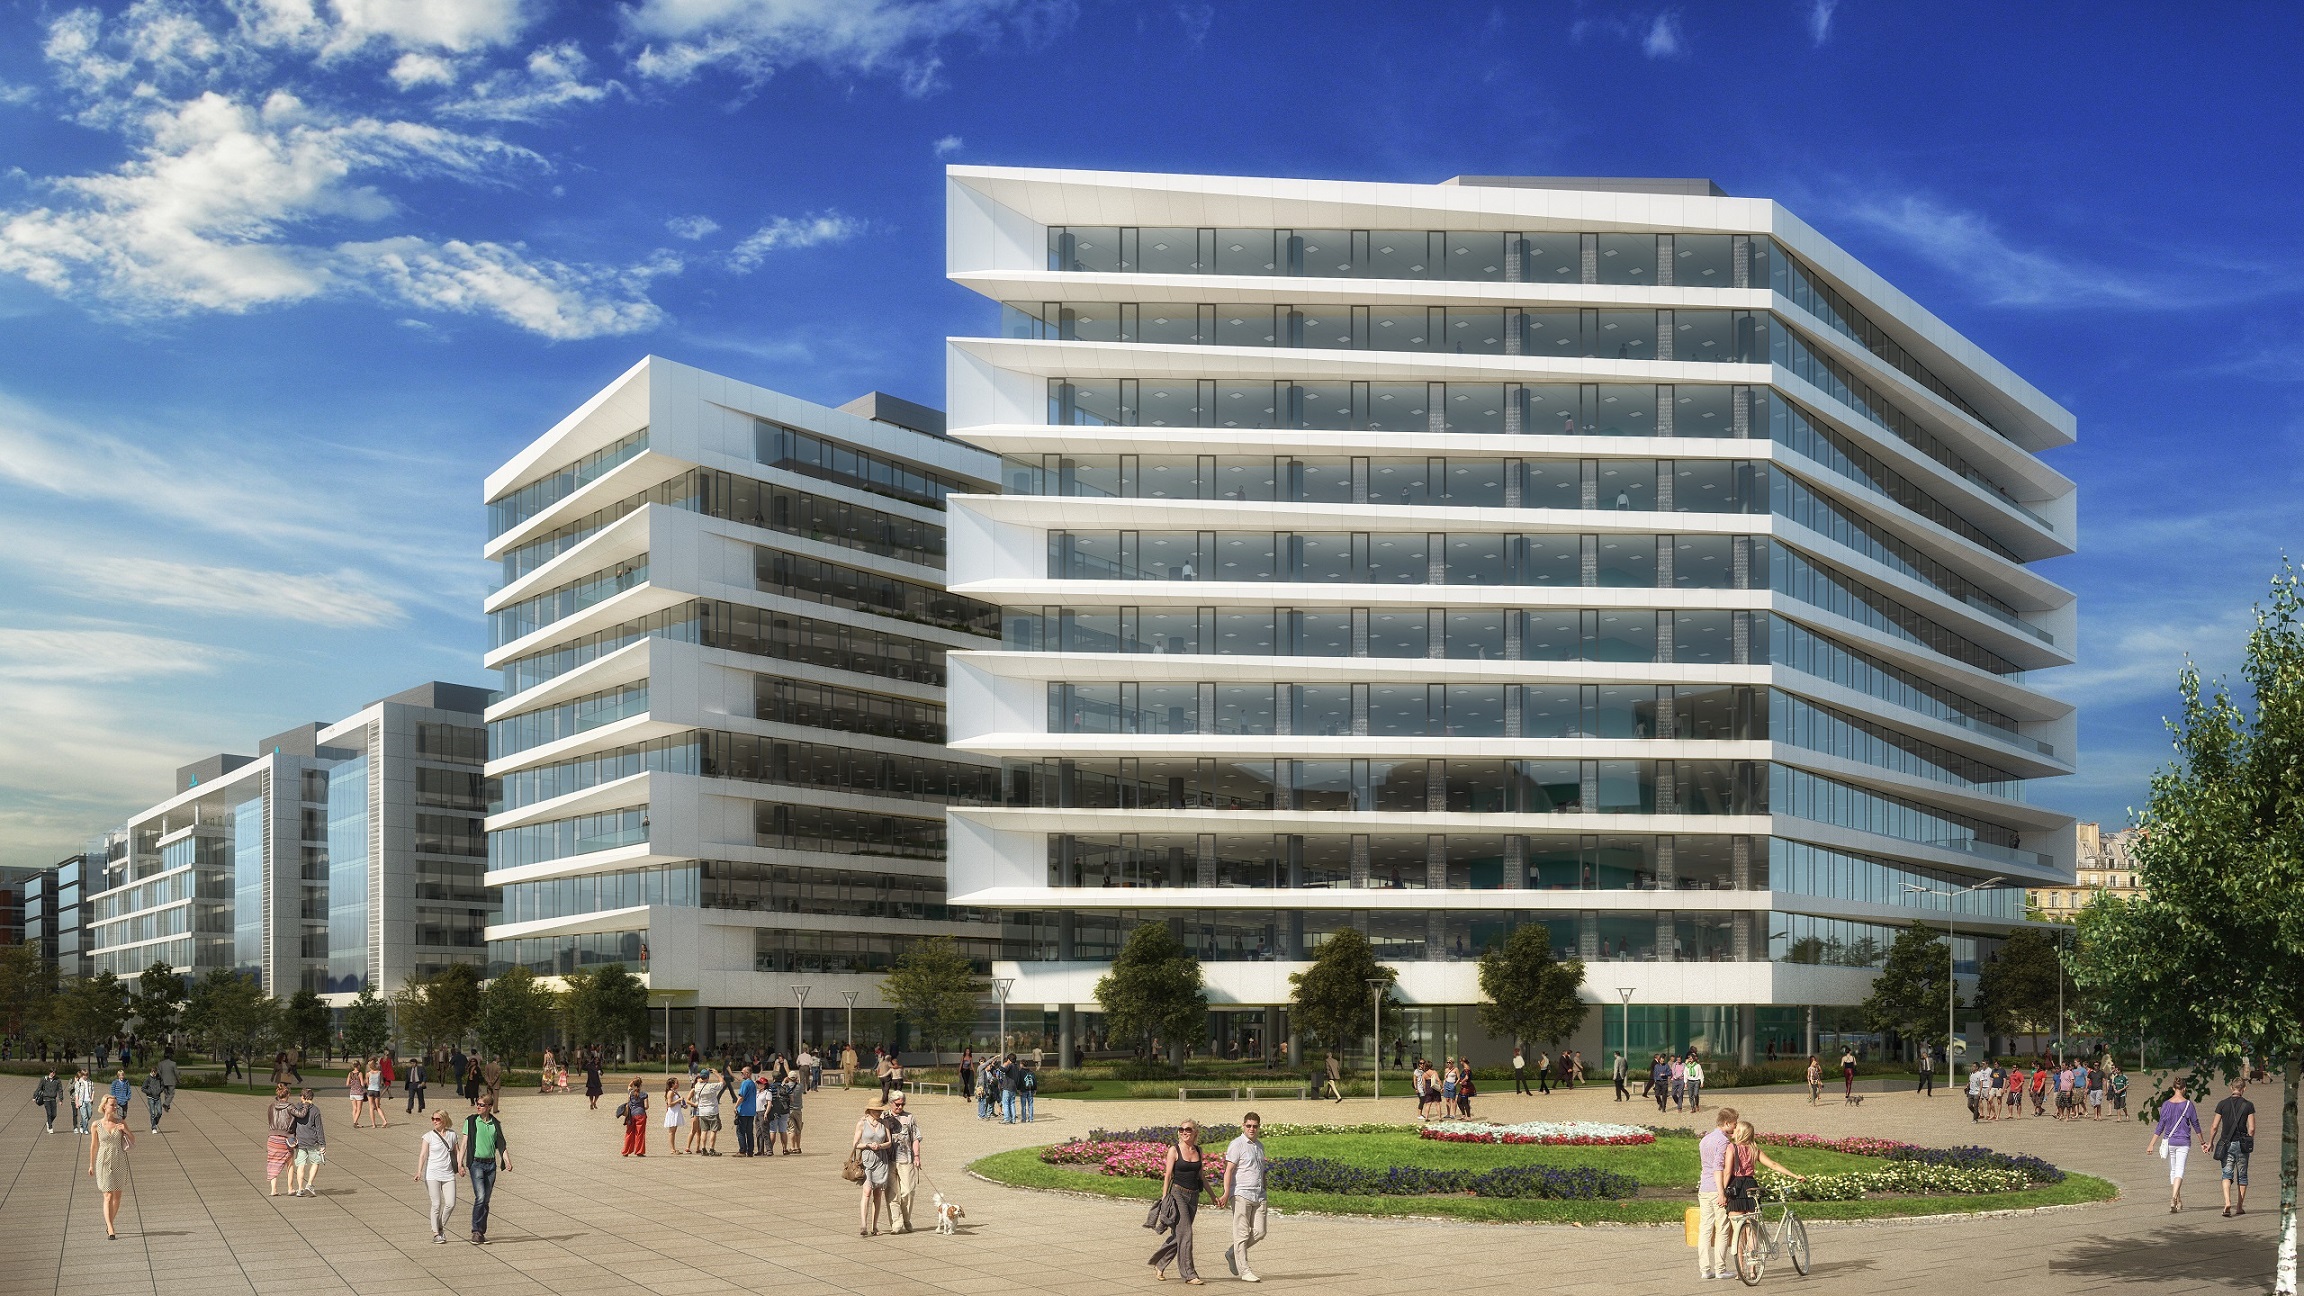
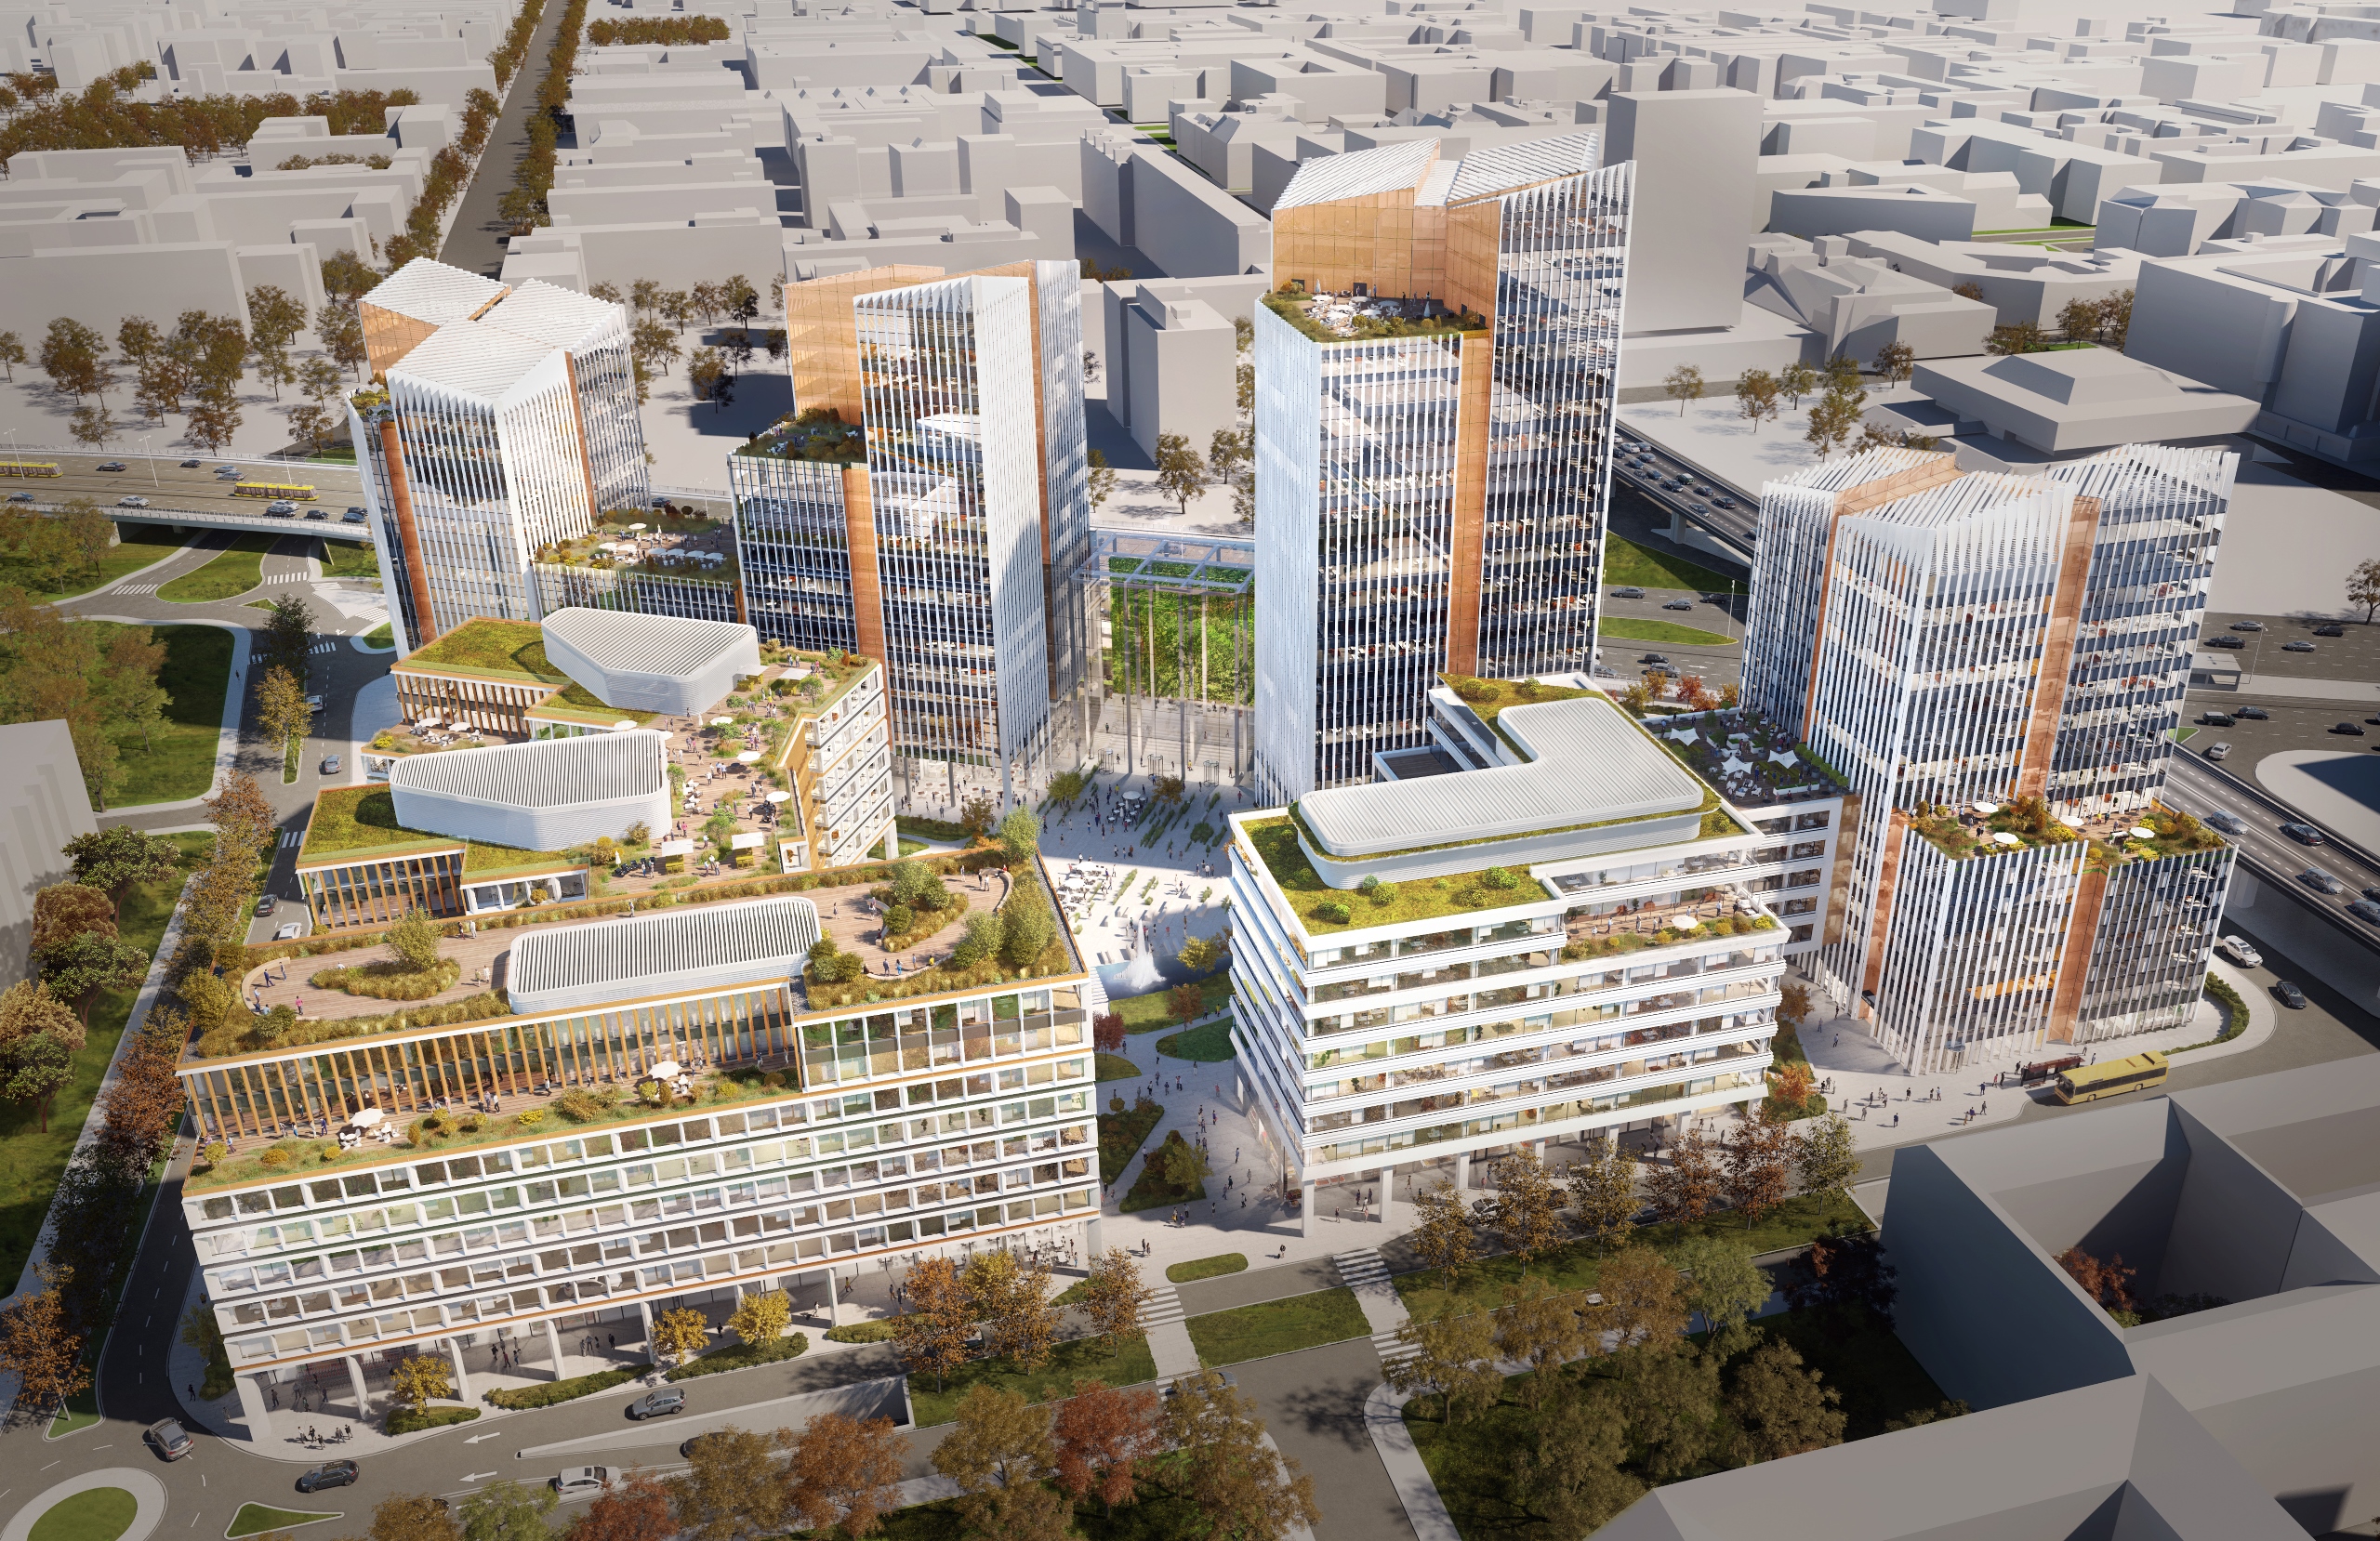
Millennium Gardens by TriGranit
Jan Hübner, County CEO for Hungary, HB Reavis
Central European markets are now playing an ever increasing role and had the best-performing markets in Europe. Last year overall transaction volumes amounted to €10.7 billion, an exceptional increase of 35%, whereas Hungarian and Slovak markets grew even by 115% and 135%, respectively. In Poland, leases sustainable in the long term remain the key drivers. Transaction volumes in the Czech Republic have already reached their highest level ever. The Czech investment market benefited from investors seeking diversification from Poland. Record investment volumes were booked in the Slovak real estate market. Its strong performance is attributed to improving liquidity and attractive opportunities compared to other CEE markets. Investor momentum and the appetite for high-yielding products lead to something of a revival in the Hungarian real estate market. One of the major trends here is the increasing interest in the work-life balance of our developments’ end-users. Historic wage competitiveness remains an additional factor contributing to attractive rent levels for BPO/SSC operators in major CEE capitals. Currently competing, Warsaw and Budapest are trying to attract financial service sector activity from post-Brexit London. Supply still appears robust, so we foresee rising vacancy rates in Warsaw and Bratislava, which will very much remain tenants’ markets. However, lower vacancy rates are predicted in Budapest. The very low new supply in Prague pushes vacancy down.
Wing’s primary focus is on Budapest. The current property market fundamentals, including vacancy rates and demand in the near future support a healthy level of development. The Hungarian economy is growing, and Budapest is both the hub for the national economy as well as an increasingly important regional centre. Several years of reduced activity compared to other Central European capitals allow for ongoing sustainable levels of development. Budapest currently enjoys a comparative advantage as an investment destination further augmenting the attractiveness of development activity. Tenants in the region remain focused on both the efficiency and the attractiveness of their workspaces for their current and potential employees. This is particularly true in a strong employment environment where they are competing for the best talent, and „soft” elements are used as an additional incentive. Location remains key, both regarding public transport access and availability of services in the immediate vicinity. Finally, tenants are increasingly environmentally aware in all areas of their activities, and look for this to be reflected in both the buildings themselves as well as in the operation of these buildings. Until 2008 the CEE region (or at least the V4) countries were viewed as a homogeneous block. Today it is understood that they share certain key attributes and challenges, but it is also clear that their markets are strongly differentiated. The relative lack of activity in the Hungarian market compared to its neighbours several years ago represents an advantage today, as demand is strong and domestic and international investors are eager for opportunities.
Globalworth announced the signing of a lease agreement with B+N Integrated Facility Services, part of the international facility management company LIWO Group, which operates across nine European countries. B+N will occupy approximately 1,500 sqm of office space in Green Court D, Globalworth’s newest development in Bucharest, currently under construction in the Aurel Vlaicu area and scheduled for completion in 2027.
UDH, one of Poland’s largest distributors of premium imported beers, has leased approximately 1,400 sq m of modern warehouse and office space at the Park Rysy Kraków distribution centre. The tenant, which has chosen to expand its operations in southern Poland, was once again represented by AXI IMMO.
Golden Star Estate has secured a long-term lease agreement with global technology solutions and consulting provider C&F for nearly 1,900 sqm of office space at the Konstruktorska Business Center. Following the transaction, the property, located in Warsaw’s Mokotów business district, is now almost fully leased. The Polish branch of C&F will officially relocate to the facility at the beginning of 2027.
New appointments
Indotek Group has announced the appointment of Diederik Bakker as Group Chief Investment Officer and Group Head of Asset Management. In his new role, the Dutch real estate investment professional will gradually assume responsibility for the company's ITAM (investment, transaction, and asset management) activities across 12 European countries, supporting the next phase of Indotek Group’s growth. His focus includes facilitating sound investment decisions across Europe and developing a group-level portfolio management strategy that combines local market knowledge with international asset management know-how.
Peakside Capital Advisors has appointed Bogi Gabrovic to advise the board and support its investment and acquisition activities in Poland. Gabrovic brings more than 25 years of CEE real estate experience to the role, having previously held senior executive positions at CTP, Golub & Company, and White Star Real Estate, where she managed transactions exceeding €2 billion.
Katarína Brydone, Jana Vlková and Vendula Maršová have been appointed as the first Equity Partners of Colliers’ Czech business. Brydone brings more than 20 years of experience in international real estate. Vlková has more than 25 years of experience in commercial real estate. Maršová, Partner and Head of Valuation and Advisory Services, brings more than 16 years of experience in real estate valuation and advisory.
The Polish Chamber of Commercial Real Estate (PINK) has published aggregated data on the Warsaw office leasing market for Q3 2026. The figures are sourced from advisory firms active in the commercial real estate sector, including Avison Young, Axi Immo, BNP Paribas Real Estate Poland, CBRE, Colliers, Cushman & Wakefield, JLL, Knight Frank, Newmark Polska and Savills.
More than 636,000 homes were completed in Romania between 2016 and 2025, equivalent to almost 33 new homes per 1,000 inhabitants, according to an analysis by Cushman & Wakefield Echinox. Romania recorded 32.9 completed homes per 1,000 inhabitants over the decade, placing it close to Germany (33.6), Slovakia (34.4) and Czechia (31.5), and ahead of Hungary (18.2), Spain (16.4) and Portugal (15.7). Residential construction intensity was considerably higher in Finland (62.8), Poland (55.2) and France (52.8).
EQT Real Estate has signed a long-term lease for the entire larger hall at EQT Park Prague North with Ecologistics, the Czech branch of a logistics company that is part of Goodcang Holdings. The hall covers 44,500 sqm and will be used for local and cross-border e-commerce fulfilment services. The interior is currently being fitted out to the tenant's requirements, with operations expected to commence over the coming months. The park's smaller hall, measuring 12,100 sqm, remains available for lease.
Property Forum is a leading event hub in the CEE real estate industry with over 10 years of experience. We organise conferences, business breakfasts and workshops focused on real estate, in London, Vienna, Warsaw, Budapest, Bucharest, Bratislava, Prague, Zagreb and Sofia, amongst other locations.
I have read the Privacy Policy of International Property Network Inc. and I consent to International Property Network Inc. sending me newsletters and managing my personal data provided for this purpose.