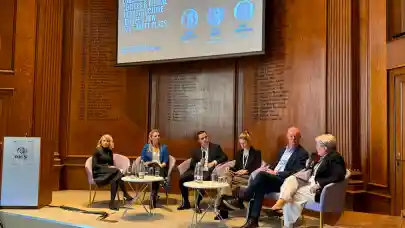
The boundaries between real estate and infrastructure are becoming increasingly blurred as power, connectivity and operational capacity emerge as critical factors in investment decisions. At the Real Estate Capital & Investment Decisions Forum 2026 in London, co-organised by Property Forum and RICS, experts discussed how logistics, data centres and transport infrastructure are converging, and why flexibility will be essential as technology and occupier requirements continue to evolve.
Andrew Dickman, Chairman at Tritax Big Box Developments, described logistics as an asset class that has evolved from industrial property and warehousing into critical infrastructure, increasingly overlapping with data centres. Tritax assesses opportunities individually, looking not only at their logistics potential but also at attributes such as power availability, fibre connectivity and location that could support alternative uses. This approach also extends to its substantial land bank, where infrastructure is planned well ahead of development to provide occupiers with greater certainty around delivery. Dickman expects data centre valuation to evolve as operational efficiency becomes increasingly important, while power and other scarce infrastructure will themselves carry greater economic value. For future investments, flexibility is central: sites should work for their intended use today but retain characteristics that allow them to adapt as technology and demand change.
Sophie Dracup MRICS, Head of Asset Management, UK at Realterm, highlighted important differences between logistics and data centres from an investment perspective. Logistics offers a broad spectrum of risk and return profiles, while a completed and leased data centre with a long, index-linked contract can behave more like a bond. Development presents a very different risk profile, with power, planning and securing an end user all needing to align. Realterm's strategy focuses on transportation-advantaged properties such as air cargo facilities, truck terminals, cross docks and industrial open storage, particularly assets that are difficult to replicate because of their location, specification, power or planning status. Dracup also expects the divide between prime and secondary logistics to widen as occupiers demand more sophisticated facilities capable of accommodating automation.
Tadhg Murphy, Vice President | Investments at Echelon Data Centres, said data centres are increasingly entering capital pools traditionally occupied by conventional real estate, although the sector has not yet fully matured into a core asset class. One of the biggest challenges is not simply securing a customer but delivering capacity afterwards, with developers facing limited contractor availability, long equipment lead times and supply-chain constraints. Geography is also changing. Europe's established hubs of Frankfurt, London, Amsterdam, Paris and Dublin remain important, but improved fibre connectivity and the rise of AI workloads are making locations further from traditional clusters increasingly viable. AI applications are generally less sensitive to latency than cloud workloads, potentially opening markets with cheaper power and greater land availability, including the Nordics and Spain. However, Murphy stressed that speculative development outside established hubs remains risky and new locations are more likely to be driven by specific customer requirements.
Nikki Venetsanakis, Senior Director - PMC Programme Lead at Linesight, identified infrastructure certainty as one of the most important determinants of whether a data centre project can actually be delivered. Power, connectivity, permits and supply chains increasingly matter more than the building itself, particularly when projects can take five to seven years to materialise. With data centre campuses moving from megawatt to gigawatt scale, simply identifying nearby grid capacity is no longer enough. Investors and developers need to understand how much power can ultimately reach a site, when it will become available and whether it can scale with future requirements. Venetsanakis argued that infrastructure therefore provides much of the underlying value of a site because it can allow developers to pivot between different uses if technology or demand changes. This flexibility will become increasingly important as AI rapidly changes data centre design, cooling requirements and capacity needs.
Mirela Calota, Transport Infrastructure Deals Lead at KPMG UK, placed the discussion in a wider infrastructure context, arguing that power, transport and digital infrastructure should increasingly be considered together rather than as separate investment categories. She highlighted growing investor interest in ports, marinas and car parks, where real estate, mobility, energy and digital services increasingly overlap. Rail is another area where she expects substantial investment in the UK and across Europe, creating opportunities around multimodal transport and logistics infrastructure. Looking ahead, Calota expects well-connected land around rail terminals, ports, airports and road networks to become particularly valuable. She also highlighted opportunities to connect infrastructure systems more efficiently, including potentially using waste heat generated by data centres elsewhere in the built environment.
The discussion, chaired by Susanne Eickermann-Riepe FRICS, Senior Vice President at RICS, pointed to a fundamental shift in how logistics and digital infrastructure assets are assessed. Land remains important, but access to scalable power, connectivity, transport networks and reliable delivery timelines is increasingly determining where investment can take place. At the same time, rapid technological change makes it difficult to predict exactly what occupiers will require a decade from now. The panel's common message was therefore to build flexibility into assets and infrastructure from the outset, allowing them to respond as technology, automation and customer requirements evolve.