From London's £20 billion investment pipeline to regeneration projects in Newcastle and Cardiff, UK cities are finding new ways to attract capital, bridge development viability gaps and turn economic ambitions into investable opportunities.
UK cities are having to work harder to secure investment as higher financing costs, development viability challenges and increasingly selective capital reshape the market for real estate and regeneration.
The challenge extends beyond attracting investor interest. Local authorities and investment agencies must demonstrate that projects are commercially viable, that infrastructure and planning requirements can be addressed, and that public- and private-sector partners have the capacity to deliver.
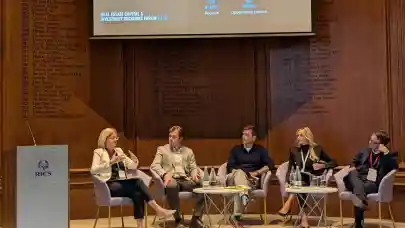
These themes emerged during a panel discussion on “The Future of Cities, Connectivity & Capital” at Property Forum's Real Estate Capital Investment Decisions Forum 2026 in London.
Moderated by Courtney Fingar, Strategic Advisor for FDI at Property Forum, the session brought together Jace Tyrrell, Chief Executive of Opportunity London; Richard Dawson, Economic Advisor, Inward Investment, at Newcastle City Council; Juliet Gamlin, Inward Investment Manager at Invest in Cardiff; and Sam Markey, Founder and Managing Director of Recurve.
Even London, with its global profile and deep pool of international investors, is adapting to a more demanding investment environment. Opportunity London, a public-private partnership working with the capital's local authorities and major property industry players, has assembled a pipeline of approximately £20 billion in real estate and real asset opportunities.
According to Tyrrell, the organisation initially focused heavily on housing, regeneration and build-to-sell developments. Investor demand has since broadened towards other asset classes, including the experience economy, knowledge-intensive activities and projects linked to artificial intelligence.
Stadiums, sporting venues and immersive entertainment are attracting interest, alongside real estate connected to universities and other knowledge-economy institutions.
But the economics of major residential and regeneration projects remain challenging. Tyrrell said the cost of capital is forcing public-sector partners to take a more active role through land contributions, equity and bridging finance.
The scale of the international market remains substantial. Tyrrell cited approximately £15 billion in annual cross-border real estate transactions in London, with the United States accounting for around half.
The organisation is increasingly targeting specific categories of investors, including US university endowments and family offices, rather than relying solely on conventional institutional capital.
For Newcastle, the challenge is particularly acute where former industrial land requires substantial remediation before private development becomes commercially attractive.
Dawson argued that cities must be candid with investors about these constraints and demonstrate a credible plan for overcoming them.
Newcastle's experience with its 2012 City Deal illustrates how targeted public investment can unlock longer-term development.
Under the agreement, the city retained business rates generated across three accelerated development zones and used approximately £100 million in borrowing to fund remediation and infrastructure works.
The intervention has subsequently supported the delivery of more than 1 million square feet of commercial space, Dawson said. The original borrowing has been repaid, while the arrangement is expected to generate a surplus for reinvestment in regeneration and economic development through 2038.
The example underlines the importance of addressing development risks before taking projects to market.
Dawson also identified a potential role for local government pension funds in supporting regional investment. However, he acknowledged the difficulty of developing opportunities that meet institutional investment requirements.
For larger international investors, scale presents another obstacle. Individual development sites may be too small to attract sovereign wealth funds or other major institutions, creating a case for combining projects into larger portfolios.
Cardiff is similarly using public-sector intervention and coordinated investment planning to strengthen its appeal to developers and occupiers.
Gamlin described how the ten local authorities within the Cardiff Capital Region have worked together to establish an investment framework and develop a shared proposition.
A major component is the £160 million Cardiff and Newport Investment Zone, centred on the compound semiconductor industry.
The initiative connects Cardiff's research and innovation capabilities with semiconductor manufacturing activity in Newport, creating what Gamlin described as a “clicks to chips” corridor.
The wider strategy links investment in high-value industries with skills, transport and urban regeneration.
In Cardiff Bay, a new 16,500-seat arena is intended to help reconnect the waterfront with the city centre. The first phase of Cardiff Crossrail, part of the wider regional metro program, is also under development to improve access between key locations.
Gamlin pointed to the transformation of the area around Cardiff Central station as evidence of what coordinated investment can achieve.
A regeneration program involving public authorities, developer Rightacres and Legal & General has attracted approximately £1 billion in investment, bringing major occupiers including the BBC, HMRC and Legal & General itself.
However, Cardiff continues to face viability challenges, particularly where development costs exceed the returns supported by local rents.
Gamlin said the city is seeking to reduce these gaps by investing in infrastructure, preparing publicly owned sites and using planning and funding mechanisms to make projects more attractive to developers.
The issue is becoming increasingly pressing for corporate inward investment: a shortage of new commercial office space could limit Cardiff's ability to accommodate large occupiers, even where demand exists.
Alongside project viability, the discussion highlighted the need for cities to rethink where investment capital might come from.
Markey argued that successful investment strategies increasingly depend on collaborative place leadership, with local authorities, universities, major employers and communities working around a shared economic proposition.
Generic claims about strengths in sectors such as advanced manufacturing are unlikely to distinguish one location from another. Investors need to understand the specific capabilities and opportunities that make a city competitive.
He also questioned whether UK cities are overlooking potential investment partners by concentrating too heavily on familiar international markets.
Latin America was one example. Markey suggested that the region's private wealth and its cultural and educational connections with the UK could support stronger investment relationships, although these have not yet been fully developed.
The discussion also highlighted a broader shift towards targeting particular investor categories, including family offices, university endowments, pension funds and impact-oriented capital. For cities seeking investment, understanding the motivations and requirements of these different groups is becoming as important as identifying the right geographic markets.
Greater local control over investment decisions and financial resources was another recurring theme.
Speakers broadly welcomed the prospect of further devolution, particularly where it could give cities more flexibility to retain locally generated revenues, finance infrastructure and support commercially viable development.
Tyrrell argued that this should not be framed as a competition between London and other UK cities. All would benefit from greater capacity to fund the infrastructure required to attract private investment.
But devolution alone will not eliminate the challenges. Higher borrowing costs, construction inflation, complex land ownership and uncertain development returns continue to affect projects across the country.
The panel's examples suggest that the cities best positioned to attract investment will be those able to combine a distinctive economic proposition with credible delivery mechanisms.
That means preparing sites, addressing infrastructure constraints, demonstrating a track record of successful partnerships and identifying capital sources suited to the scale and risk profile of individual opportunities.
As international investors become more selective, the ability to turn a promising location into an investable proposition is emerging as a defining competitive advantage for UK cities.